Thursday, November 5, 2026

Nvidia Projects $1 Trillion in Chip Sales Through 2027 as AI Semiconductor Race Accelerates

Nvidia forecasts $1 trillion in chip sales through 2027 as the AI semiconductor industry expands manufacturing capacity and diversifies architectures. The market is shifting beyond traditional silicon with photonic computing startups like Olix planning 2027 product launches, while Micron expands high-bandwidth memory production to meet surging AI infrastructure demand.

LM Salvado
LM Salvado

March 18, 2026

Nvidia Projects $1 Trillion in Chip Sales Through 2027 as AI Semiconductor Race Accelerates
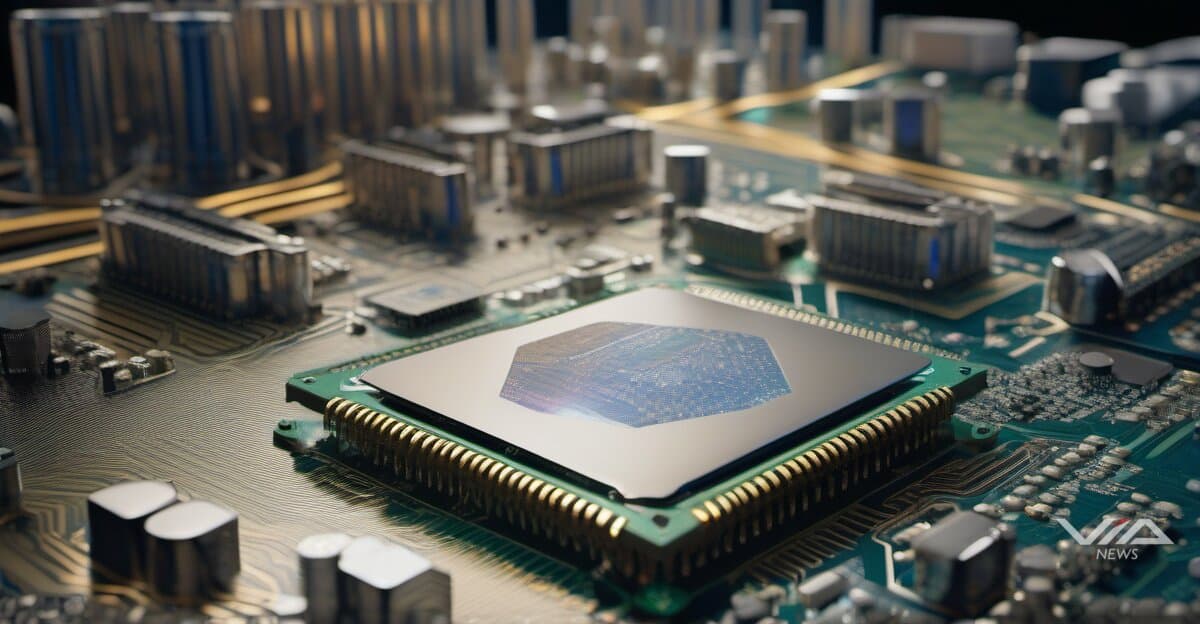
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.
Loading stream...

Nvidia projects $1 trillion in chip sales through 2027, marking a surge in AI semiconductor demand as hyperscalers build out training and inference infrastructure. The forecast reflects accelerating investments across the chip ecosystem, from traditional GPU manufacturers to emerging photonic computing players.

Micron is expanding high-bandwidth memory (HBM) production facilities to address capacity constraints in AI chip manufacturing. HBM serves as critical infrastructure for AI accelerators, with advanced packaging technologies becoming a key bottleneck as chipmakers race to deliver higher-performance solutions.

The semiconductor market is diversifying beyond established silicon architectures. Olix plans to ship its first photonic computing product in 20271, joining POET Technologies in pursuing optical solutions for AI workloads. These alternatives target power efficiency gains as traditional transistor scaling faces physical limits.

Specialized AI accelerators are carving out distinct market segments. Amazon's Tranium chips and dedicated Language Processing Units (LPUs) focus on inference workloads, where cost per query matters more than raw training performance. This specialization reflects maturing AI deployment patterns as companies move from model development to production.

The investment wave spans the entire supply chain. Foundries are adding advanced node capacity while equipment makers develop next-generation lithography tools. Packaging specialists are scaling chiplet integration capabilities to enable multi-die AI processors with improved memory bandwidth.

Market dynamics favor companies with integrated design and manufacturing control. Nvidia maintains architectural leadership in training workloads, while competitors pursue cost advantages through application-specific designs. The photonic computing segment remains speculative, with commercial viability dependent on solving integration challenges with existing silicon infrastructure.

Through 2027, the semiconductor industry faces competing pressures: explosive AI demand versus cyclical memory markets and geopolitical supply chain risks. Companies balancing near-term capacity expansion with long-term architectural bets will shape the next infrastructure cycle.
Source documents

Via News is a conduit. We point to the source documents behind this report — we don't replace them. Trace any claim to its source and decide what to trust. How we source

Source Trace Score3 source documents3 with a live linkVerifiability: Strong
  1. [1]News articleCrunchbase News
    While OpenAI Shattered Records, Robotics and Semiconductor Startups Quietly Added The Most New Unicorns In February
  2. [2]Press releaseGlobeNewswire· March 13, 2026
    D’importants investissements dans l'infrastructure de recherche placent le Canada en tête de l'innovation mondiale
  3. [3]News articleYahoo Finance· March 16, 2026
    Stock market today: Dow, S&P 500, Nasdaq jump to start week, oil slides amid Trump's warning to allies on Iran

In this story · Knowledge Files

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Oncology Data Season and Biotech Capital Allocation: ESMO Readouts, Ivonescimab PDUFA, and Diverging Corporate Moves
Late-2026 biotech is driven by a dense catalyst calendar. ESMO 2026 delivers data from ivonescimab, Enhertu, R-DXd and bemarituzumab, and the FDA has set a 14 Nov PDUFA date for the ivonescimab BLA. Capital allocation is diverging. Krystal Biotech authorized a $400M buyback while lowering FY2026 spend guidance and pushing milestones into 2027. Spago is moving to delist from Nasdaq First North. The facts are clinical and corporate events, not AI or fintech, so the finance angle is limited to capital markets (buybacks, guidance, delistings, regulatory timelines).
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
Ford Motor Company
Both facts give cash for Ford Motor Company at the same point in time (2025-12-31; FY 2025 year-end and Q4 2025 year-end are the same date). Both are labelled USD, but the values are 23,356,000,000 and 23.356, which cannot both be true in USD. The two numbers agree once the second is read as billions (23.356 bn = 23,356,000,000), so the economic content is consistent and the conflict is a unit/scale error in the Q4 2025 record. The period is not the reason for the conflict: a Q4 and an FY figure at the same year-end date should match.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,995
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,995 facts checked against source5,549 source documents archived
Query this data → isubstrate.com