
Saturday, September 19, 2026

TSMC's Taiwan Concentration Creates Geopolitical Risk Despite AI Chip Dominance

TSMC dominates AI chip manufacturing as the central supplier to the AI infrastructure buildout, posting record profits. Despite fair value assessments showing 7.3% undervaluation at $400, concentrated production in Taiwan creates geopolitical single-point-of-failure risk that may compress valuations regardless of strong fundamentals.

LM Salvado
LM Salvado

April 12, 2026

TSMC's Taiwan Concentration Creates Geopolitical Risk Despite AI Chip Dominance
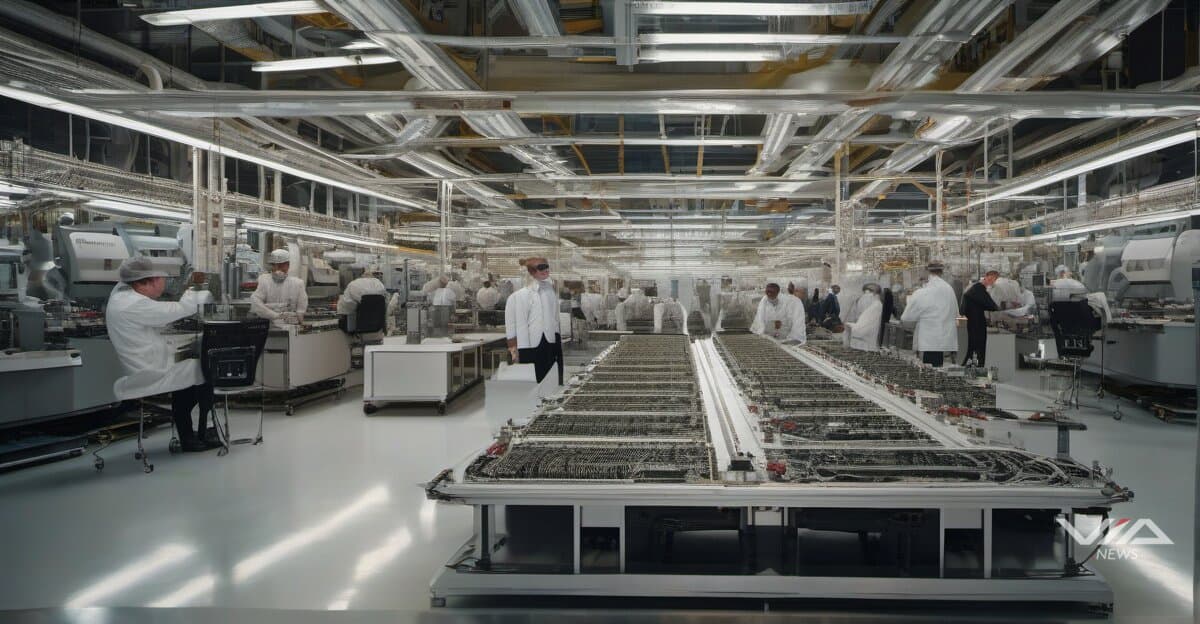
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.
Loading stream...

TSMC operates as the central pillar of the global semiconductor ecosystem powering the AI revolution, supplying chips to the AI infrastructure buildout with record profits and dominant client relationships.1 The company's position as the primary manufacturer for AI chip designs creates unprecedented market power.

Analysts assess TSMC's fair value at $400 per share, representing 7.3% undervaluation despite its strong positioning in AI chip production.1 This valuation acknowledges the company's technical leadership and customer relationships across the semiconductor industry.

The concentration of TSMC's production facilities in Taiwan presents a geopolitical shock risk that overshadows operational strength.1 A single geographic location houses the manufacturing capacity for most advanced AI chips, creating vulnerability to regional instability.

Amazon's announcement of increased 2026 capital expenditure guidance signals continued demand growth for TSMC's manufacturing services.1 The AI infrastructure buildout drives customer commitments to long-term production capacity.

TSMC's heavy AI-focused capital expenditure plans increase exposure to potential demand shifts in the sector.1 Large-scale investments in cutting-edge fabrication capacity lock the company into current technology trajectories and customer requirements.

The hypothesis predicts valuation multiple compression relative to semiconductor peers during geopolitical tension events, even as fundamentals remain strong.1 Taiwan Strait incidents may correlate with increased TSMC stock volatility independent of operational performance.

Customer diversification efforts and alternative fabrication location announcements will test whether TSMC can reduce geographic concentration risk.1 Forward price-to-earnings ratios may diverge from fabless chip designers with geographic diversification as investors price in geopolitical premium.

The market faces a tension between TSMC's irreplaceable role in AI chip manufacturing and the concentration risk inherent in Taiwan-based production. Strong fundamentals may not prevent valuation pressure if geopolitical concerns intensify.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Network, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
AI Boom Hits a Fork: Slowdown Calls Clash with Capex Confidence as Markets Get Nervous
Dario Amodei's repeated calls for a global slowdown in frontier AI development, echoed by Microsoft's new humanist AI code of conduct and FTC antitrust caution, are being publicly rejected by Nvidia and Meta leadership even as hyperscaler spending draws fresh skeptical scrutiny (Wachter's analysis, Burry-style overbuilding worries) and weak guidance from Adobe and a post-slowdown-comment selloff in GE Vernova signal investor jitters. Meanwhile wealth and security effects of the AI race keep compounding — Zhang Yiming's fortune surging on AI-driven ByteDance value, a Chinese hacking firm weaponizing AI against stolen government secrets, and low-quality AI-generated products (an AI sitcom, a spam-flooding agent platform) fueling backlash even as adoption races ahead.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
Berkshire Hathaway
Both facts report Berkshire Hathaway's cash position on 2026-01-01 with identical observation timestamps, but claim vastly different values: 380 billion USD vs 400 USD. These cannot both be true for the same entity at the same point in time. The magnitude of the discrepancy (a factor of ~10^9) rules out rounding, unit conversion, or methodological differences.
We flag conflicts openly ›
Recently verified
Checked against the original source
4,982
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,982 facts checked against source5,299 source documents archived
Query this data → isubstrate.com