
Thursday, October 22, 2026

Nevada Data Centers Set to Consume 35% of State Electricity by 2030, Forcing Utility Repricing

A 2026 study projects Nevada data centers will account for 35% of state electricity consumption by 2030. AI infrastructure demand is crossing from a niche concern into a systemic grid-level constraint. The shift is accelerating capital flows into utilities, power generation assets, and energy-focused REITs.

LM Salvado
LM Salvado

May 28, 2026

Nevada Data Centers Set to Consume 35% of State Electricity by 2030, Forcing Utility Repricing
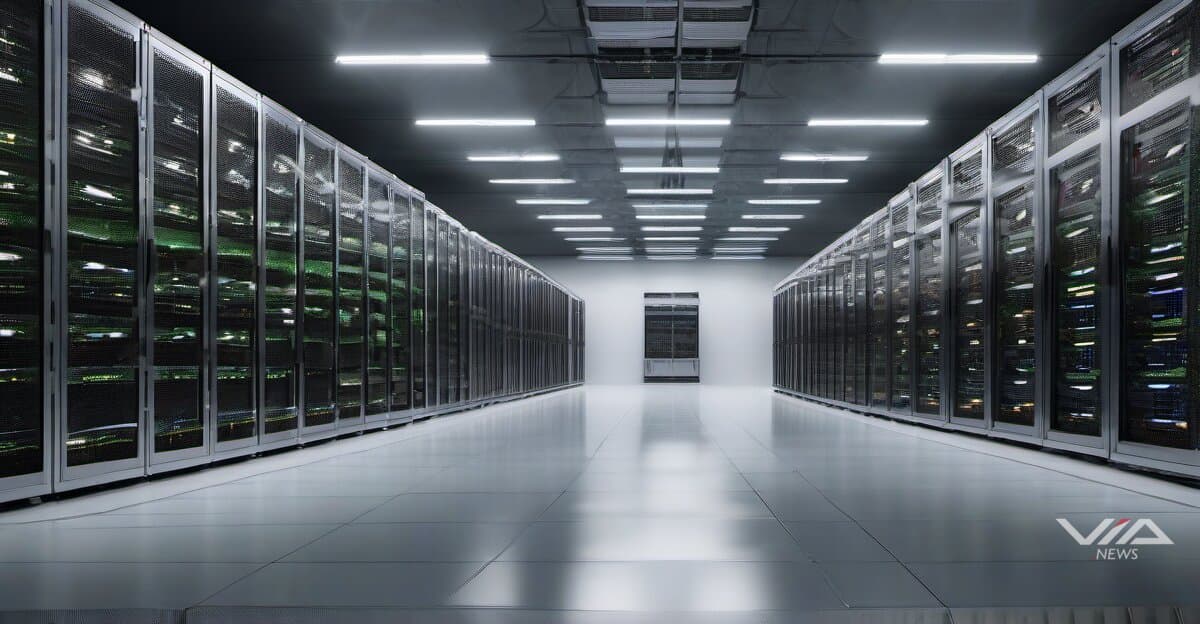
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.
Loading stream...
1 That single number reframes the investment thesis for utility stocks and power REITs across the United States.

AI data center power demand is no longer a niche concern. It is becoming a structural constraint on regional grids. The Nevada projection illustrates a dynamic playing out in Virginia, Texas, and Arizona: concentrated hyperscaler investment outpacing local generation capacity.

For utility investors, the implications are direct. Utilities serving high-density data center corridors face accelerating capital expenditure requirements. New transmission lines, substation upgrades, and peaker capacity are needed ahead of demand. Rate base growth follows — historically a positive for regulated utility earnings.

Power generation REITs stand to benefit from the same dynamic. Contracted capacity agreements with hyperscalers are becoming a structural revenue stream. Natural gas, nuclear, and utility-scale solar assets in constrained geographies carry increasing scarcity value.1

The pressure runs in both directions. Margin compression is emerging for hyperscalers as electricity costs rise in supply-constrained markets. Data center development timelines are extending in geographies where grid interconnection queues are measured in years, not months.

Energy infrastructure M&A is accelerating as a result. Utilities, natural gas pipelines, and nuclear operators are attracting strategic interest from data center operators seeking to lock in long-term power supply.1 Several nuclear restart projects have gained commercial momentum directly tied to AI demand commitments.

The structural shift creates a bifurcated opportunity set. Utilities with existing capacity headroom and fast-track permitting environments gain pricing power. Those in already-constrained grids face regulatory and political friction on rate increases even as capital needs grow.

For REIT investors, power infrastructure — historically a niche within real assets — is repricing toward data center-adjacent valuations in markets where electricity access is the binding constraint on AI capacity expansion.AI compute demand forecasts have consistently been revised upward. Grid planners and utility investors who anchor to current load curves risk underestimating the capital deployment cycle ahead.
About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Biopharma Catalyst Crunch: Late-Stage Readouts and Regulatory Milestones Converge on the Ivonescimab PDUFA Date
October 2026 is dense with clinical and regulatory news. Phase 3 trials hit primary endpoints (ALOFT-IPF, RESTORE-3), long-term data came out (MIUDELLA at 6 years, QUILT-3.032), and the FDA accepted Roche's vamikibart BLA. Scholar Rock resubmitted its apitegromab MAA to the EMA. The next catalysts are ESMO 2026 (Oct 23) and the Nov 14 FDA PDUFA date for ivonescimab, followed by Maritime-1 primary completion in January 2027. The speculative QAIAx items (QIII pilot, microcities patent) are a weak, tangential thread with little financial substance.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,986
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,986 facts checked against source5,426 source documents archived
Query this data → isubstrate.com
Nevada Data Centers Set to Consume 35% of State Electricity by 2030, Forcing Utility Repricing | ViaNews Market